The New Capital Wave: How Digital Lending and Private Credit are Rewriting the Economics of the Global South

DUBAI, United Arab Emirates – For the past decade, the prevailing narrative surrounding financial technology in emerging markets has been disproportionately dominated by the influx of venture capital. Silicon Valley-style equity fueled the rise of the first wave of African and Middle Eastern unicorns, subsidizing user acquisition and building the foundational payment rails of the digital economy. But as global capital markets mature and the era of zero-interest-rate policy fades into history, the macroeconomic engine driving the Global South has decisively shifted. The next decade of hyper-growth will not be underwritten by equity; it will be engineered by debt.
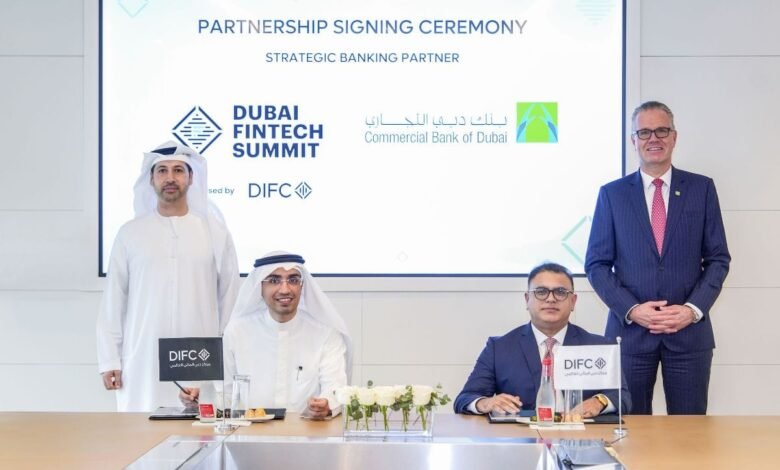
Next week, as global financial leaders, sovereign wealth managers, and regulatory architects gather at the Madinat Jumeirah for the 2026 Dubai FinTech Summit, the most consequential conversations will not center on payment gateways or consumer apps. Instead, the spotlight will be intensely focused on the convergence of two massive financial forces: the institutionalization of private credit in the Gulf, and the algorithmic precision of digital lending across the Middle East and Africa. Together, they are systematically closing the multi-trillion-dollar credit gap that has historically paralyzed the Global South.
The Structural Vacuum of Legacy Banking
To understand the explosive growth of alternative lending models, one must first examine the systemic failure of traditional commercial banking in emerging markets. For decades, legacy tier-one banks operated on a strictly binary risk model heavily reliant on physical collateral, audited historical financial statements, and traditional credit bureau reporting. Following the global financial crisis and the implementation of stringent Basel III and IV capital adequacy requirements, Western banks actively engaged in “de-risking” systematically withdrawing from emerging market corridors to avoid complex compliance burdens.
This regulatory retreat created a devastating “missing middle.” Micro-enterprises, social entrepreneurs, platform gig workers, and mid-sized logistics operations, the actual bedrock of the real economy in the Global South, found themselves entirely locked out of the formal credit system. They generated consistent cash flows and possessed viable unit economics, but because they operated in asset-light, digitally native environments, they were mathematically invisible to traditional loan officers.
The Algorithmic Shift in Underwriting
The digital lending revolution was born directly out of this friction. Armed with sophisticated machine learning models, fintech insurgents began underwriting the invisible. Rather than demanding property deeds or three years of audited tax returns, these platforms leverage alternative data telemetry: mobile money velocity, digital supply chain metrics, utility payment consistency, and vendor rating scores on e-commerce portals. By substituting relationship-based gatekeeping with algorithmic, API-driven meritocracy, they have transformed the fundamental physics of risk assessment.
Crucially, regulators in the Middle East are now institutionalizing this exact shift. Just days ago, in late October 2026, the UAE’s Etihad Credit Bureau launched a groundbreaking overhaul of its system with “Credit Score 3i.” Recognizing the massive influx of expatriate talent and digitally native businesses, the Bureau introduced a secondary, distinct scoring range (300 to 650) specifically designed for “new-to-credit” individuals and entities with limited financial histories. This is a profound regulatory milestone. It explicitly signals that emerging and thin-file borrowers are no longer considered un-scorable anomalies; they are recognized as a high-growth demographic that requires modern, tailored risk modeling. The UAE is effectively providing a regulatory blueprint for how national infrastructure can safely integrate alternative digital underwriting.
Private Credit: The Liquidity Engine of the New Silk Road
However, building an algorithmic underwriting engine is only half the equation. Digital lenders and neo-banks require massive balance sheet capital to actually deploy those loans. This is where the dramatic evolution of the Gulf’s financial ecosystem becomes the critical catalyst.
Historically, non-bank lenders in emerging markets struggled to secure wholesale funding. Today, they are tapping into the booming private credit markets of the UAE. Both the Dubai International Financial Centre (DIFC) and Abu Dhabi Global Market (ADGM) have engineered highly sophisticated, English common-law regulatory regimes tailored specifically for private credit and direct lending funds. These vehicles are aggregating vast pools of institutional capital, family office wealth, and sovereign liquidity.
For global asset managers, the math is extraordinarily compelling. As of late 2026, specialized private credit funds operating out of the UAE are targeting net risk-adjusted yields between 10.5% and 14.0% by providing direct senior secured loans, unitranche facilities, and mezzanine financing. Instead of lending directly to individual businesses in frontier markets, which carries prohibitively high diligence costs, these credit funds act as wholesale liquidity providers. They extend massive debt facilities to the continent’s leading digital lending platforms, who then utilize their algorithmic models to deploy that capital efficiently to SMEs on the ground. It is the perfect symbiosis: Gulf institutional capital seeking high-yield diversification paired with indigenous technological platforms capable of hyper-local risk assessment.
The Pivot from Consumer Debt to Productive Capital
As the Dubai FinTech Summit agenda highlights, the narrative surrounding digital lending has also profoundly matured. In its nascent stages, the sector was frequently criticized for prioritizing high-interest, short-term payday loans for consumers, leading to debt traps and regulatory backlash in key markets across Sub-Saharan Africa.
The 2026 agenda, featuring critical panels such as “Scaling Micro-Credit Globally,” “The New Capital Wave: Private Credit In The Global South,” and “Transforming Credit: Neo-Banks Driving Digital Lending” reflects a massive pivot toward productive capital. The smart money is no longer aggressively funding consumer consumption; it is financing B2B commerce.
We are witnessing the rapid scale of embedded supply chain finance. By integrating directly into procurement portals, logistics networks, and digital marketplaces, AI-driven lenders can intercept the transaction flow. When a merchant in West Africa receives a massive purchase order, the embedded platform can instantly verify the order via a cryptographic hash, underwrite the merchant’s performance history, and provide an instant merchant cash advance or invoice factoring line. This allows the business to procure inventory without waiting 90 days for traditional clearing. By injecting capital directly into the friction points of the supply chain, digital lending transitions from a consumer convenience to an indispensable macroeconomic growth engine.
A Sovereign Imperative
The geopolitical implications of this shift are immense. As traditional Western capital markets turn increasingly insular, focused heavily on domestic industrial policy and de-globalization, the Middle East is aggressively filling the void. The UAE is positioning itself not just as a wealthy neighbor to the Global South, but as its primary financial router—the indispensable bridge connecting global institutional liquidity with hyper-growth emerging demographics.
The platforms that can successfully navigate this nexus will reap generational rewards. They are building the infrastructure for a demographic dividend that comprises over a billion people. They are proving that capital can flow safely and profitably across fragmented regulatory zones when backed by programmable trust and autonomous risk modeling.
For the chief executives, venture builders, and credit portfolio managers navigating the exhibition halls of the Madinat Jumeirah next week, the strategic imperative is unmistakably clear. The era of pure digital disruption for its own sake is over. We have entered the era of scaled financial infrastructure. The democratization of capital in the Global South is no longer a philanthropic ambition; it is arguably the most lucrative, highly engineered, and consequential financial frontier of the 21st century.