Agentic AI and the ‘Invisible Bank’: When Innovation Becomes Core Infrastructure

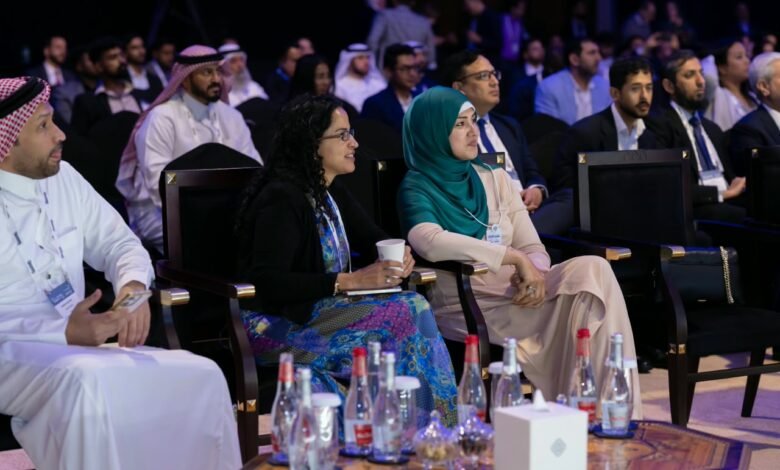
DUBAI – For the past three years, the global financial sector has been gripped by a singular technological obsession: generative artificial intelligence. Bank executives, eager to signal their modernity to shareholders, rushed to deploy AI “copilots” that could draft emails, summarize lengthy compliance documents, and generate marketing copy. But as the world’s financial elite gathered at the Madinat Jumeirah for the Dubai FinTech Summit 2026, a sobering realization permeated the sprawling exhibition floors and closed-door VIP lounges. The generative AI wave was merely the prologue. The true architectural disruption of global finance has just arrived, and it is known as Agentic AI.
If generative AI is a highly articulate intern that requires constant human supervision, Agentic AI is an autonomous, senior executive. It does not wait for a prompt; it observes, reasons, and executes complex sequences of actions across multiple systems to achieve a strategic goal. The transition from digital platforms that assist humans to intelligent platforms that act independently was the defining intellectual current of the 2026 summit.And it is accelerating the industry toward a concept that, until recently, seemed like science fiction: the “Invisible Bank”.
In an era defined by Agentic AI, the most advanced financial institutions will no longer compete on the elegance of their mobile applications or the geographic footprint of their retail branches. Instead, they will compete on their ability to embed their financial services so deeply into the background of commercial and personal life that the act of “banking” virtually disappears.
From Copilots to Autopilots: The Agentic Paradigm Shift
The sheer scale of this transition was laid bare during one of the summit’s marquee panel discussions, aptly titled, “The Future Of Finance Is Agentic: From Digital Platforms To Intelligent Action”. The panelists, comprising chief technology officers from tier-one global banks and founders of decacorn fintechs, drew a sharp distinction between the AI of yesterday and the autonomous agents of tomorrow.
Currently, a corporate treasurer managing global liquidity must manually log into multiple portals, assess currency fluctuations, and execute transfers to ensure payroll is funded across five different jurisdictions. An Agentic AI system, however, fundamentally alters this workflow. Granted role-based permissions and operating within defined risk parameters, the AI agent continuously monitors global balances, predicts cash flow shortfalls based on historical data, and autonomously executes cross-border hedging strategies and liquidity transfers before a human even realizes a deficit is looming.
The operational efficiency gained through this autonomy is staggering. According to industry data circulated at the summit, leading financial institutions deploying early-stage agentic systems are already achieving 25 to 40 percent faster loan approvals and reducing manual trade finance processing by up to 65 percent.By automating continuous, event-driven processes, Agentic AI is eliminating up to 80 percent of manual interventions in critical banking workflows. This is not simply a reduction in operational overhead; it is the total reconfiguration of how a financial institution manufactures its products.
Core Banking, Rewired: The Infrastructural Reality
However, deploying autonomous intelligence requires an infrastructural foundation that the vast majority of legacy banks simply do not possess. You cannot install a hyperspeed AI engine into a technological chassis built in the 1990s. This friction was the central theme of another highly attended summit session, “Core Banking, Rewired: How Leading Financial Institutions Are Scaling Agentic Ai”.
For decades, traditional core banking systems were designed as massive, monolithic vaults of data. They were built for batch processing, updating ledgers at the end of the business day. Agentic AI, conversely, requires real-time, continuous read-and-write access to a bank’s deepest data layers. If an AI agent is assessing real-time market risk, continuously analyzing portfolio positions to provide dynamic hedge recommendations, it cannot wait for an overnight batch update. It requires a composable, API-driven architecture where data flows fluidly and instantly.
As industry architects noted during the summit, the roadmap to an AI-native bank is grueling. It requires a massive audit of the bank’s data layer to resolve latency, establish strict data lineage, and build sophisticated orchestration engines that can monitor, authorize, and crucially pause individual AI agents if they begin to drift from their intended parameters. Institutions that fail to modernize these core systems will find themselves structurally incapable of deploying agentic technologies, permanently relegating them to the role of utility providers while agile fintechs capture the high-margin relationships.
The Compliance Conundrum: Moving at Machine Speed
The deployment of autonomous agents introduces an unprecedented regulatory and legal challenge, a tension perfectly encapsulated by the summit panel, “Ai At Machine Speed: Can Regulation Keep Up?”.
Finance is one of the most heavily regulated industries on the planet. When a human trader or compliance officer makes a catastrophic error, there is a clear chain of culpability. But if an autonomous AI agent, optimizing for yield, executes a series of rapid trades that inadvertently violates a global sanctions protocol, who is held responsible? The algorithmic model? The engineer who designed the guardrails? The chief executive?
The solution, paradoxically, lies in deploying more AI. The summit highlighted a critical pivot in how banks are approaching financial crime, discussed extensively in the session “Beyond Transaction Monitoring: Ai Investigator Agents In Financial Crime Compliance”. Historically, anti-money laundering (AML) teams relied on static rules that generated thousands of false positives, requiring armies of human analysts to review benign transactions.
Today, AI investigator agents are flipping this model. These systems autonomously correlate complex transaction patterns, behavioral data, and external risk indicators to generate comprehensive Suspicious Activity Reports (SARs) complete with full supporting documentation. By doing so, they are reducing false positive rates by 40 to 60 percent. The new regulatory paradigm requires “hierarchical explainability” the ability for a bank to instantly produce a detailed, algorithmic audit trail proving exactly why an autonomous agent made a specific decision at a specific millisecond. The Three Lines of Defense model is being radically adapted, with internal audit teams now requiring independent capabilities to assess AI governance and pause critical operations through manual overrides when agents fail.
The “10x Bank” and the Threat to the Balance Sheet
Ultimately, the rise of Agentic AI forces a profound reckoning regarding the nature of human capital in finance. We are witnessing the birth of the “10x bank,” a concept gaining massive traction among consulting heavyweights and forward-thinking executives. In this model, institutional growth is no longer constrained by headcount.A single portfolio manager or risk analyst can command a digital workforce of specialized AI agents, amplifying their individual output exponentially. The future of financial work is not about managing people; it is about designing the workflows, role-based permissions, and cultural frameworks where humans direct machine intelligence to achieve outsized results.
Yet, this intelligence will not be the exclusive monopoly of the banks. The most disruptive realization to emerge from the 2026 summit is that consumers and corporate clients will soon deploy their own Agentic AI.
Historically, banks have relied on the sheer friction of human inertia to maintain their deposit bases. Moving money between institutions to chase a slightly higher interest rate required too much manual effort for the average consumer, allowing banks to maintain wide net interest margins. Agentic AI obliterates this moat. In the very near future, a customer’s personal AI agent will constantly monitor the global marketplace, automatically shifting deposits, refinancing loans, and optimizing liquidity across multiple institutions with zero human effort.
When capital becomes intelligent and autonomous, the traditional banking balance sheet where deposits and loans drive two-thirds of revenue is suddenly under siege.Banks will be forced into a perpetual, real-time bidding war for liquidity, threatening traditional profitability models.To survive, institutions must transition from siloed product pushers into integrated, hyper-personalized advisory hubs.
The Arrival of the Invisible Bank
As the final delegates filed out of the Madinat Jumeirah and the 2026 Dubai FinTech Summit drew to a close, the consensus was clear. The future of finance is not a “super app” overflowing with buttons, charts, and notifications. The future of finance is the “Invisible Bank”.
It is a financial system embedded so seamlessly into the digital and physical world that it anticipates needs, assesses risks, and executes transactions entirely in the background. It is a world where money itself is programmable and agentic.
The institutions that attempt to simply bolt AI chatbots onto their legacy frameworks will be swiftly rendered obsolete by the sheer velocity of this shift. But for those leaders willing to endure the painful, systemic process of rewiring their core architecture, the prize is unparalleled. They will emerge not merely as digitized banks, but as the foundational operating systems of the new global economy. The era of human-speed banking is officially over; the machines have taken the wheel.